Anthropic’s IPO prospectus: the numbers that stood out
Anthropic’s IPO prospectus is out.
Revenue went from $41m in 2023 to $386m in 2024 to $4.6bn in 2025. Then in just the first six months of 2026 it did $16.3bn. That’s 14 times the same period last year, and more than three times the whole of 2025.
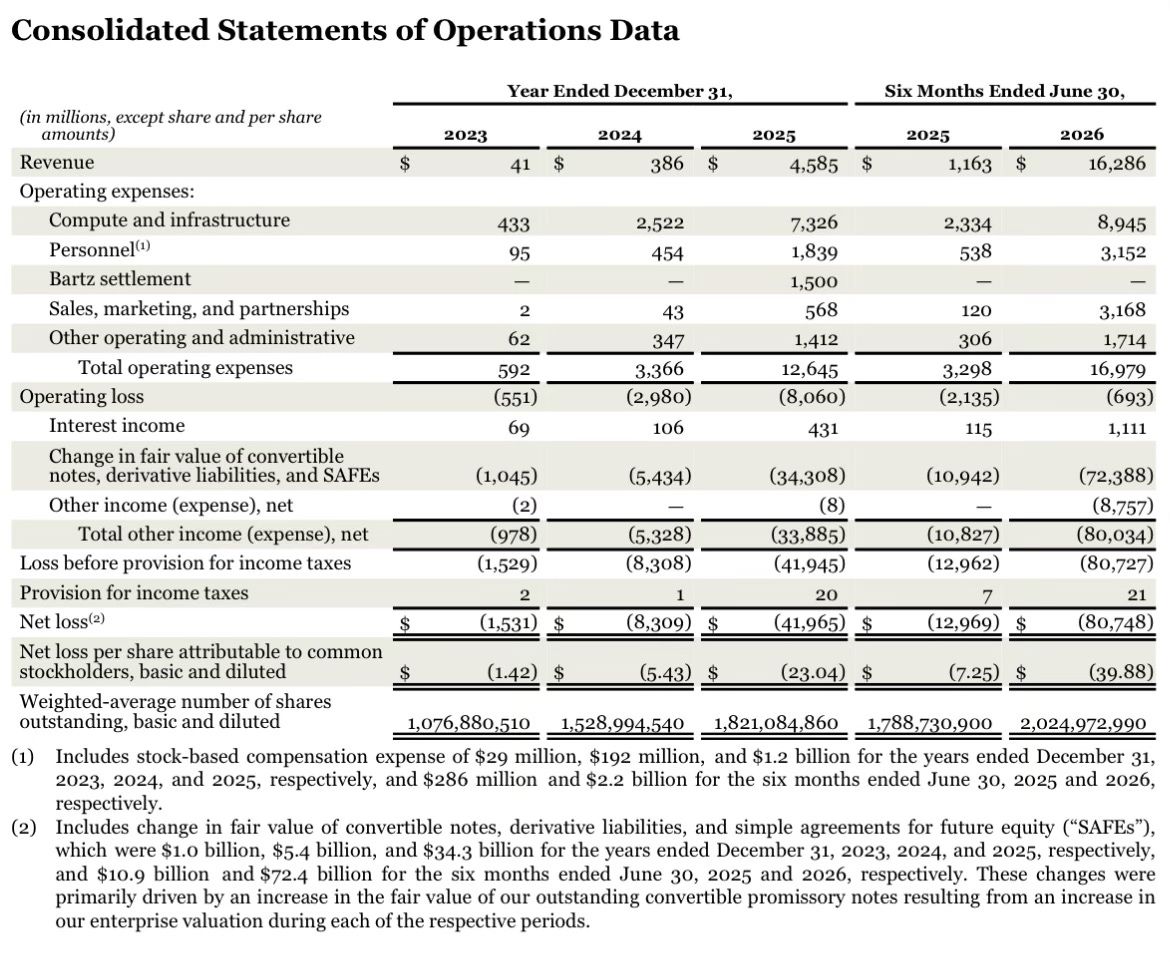
What really jumped out is that the business itself is losing less. Operating loss for the first half of 2026 was $693m, against $2.1bn a year earlier, on 14 times the revenue. Compute is the big cost at $8.9bn, which is about 55% of revenue.
As a marketer, the line I keep coming back to is sales, marketing and partnerships. It went from $120m to $3.2bn in a year, so they’re clearly buying growth as well as building it.
The headline net loss of $80.7bn looks terrifying, but $72.4bn of it is a paper charge from the rising value of their convertible notes, not cash going out the door.
Are you buying in at IPO?
Simon Hawtin
Agentic GTM leader in London, using AI agents for signal-based outbound, ABM and AEO/GEO to acquire pipeline.