Where the fundraising money went, 10 Aug to 10 Nov 2026
Most of it went to AI, and most of that in a handful of very big rounds. I went through three months of TechCrunch’s fundraising coverage, and 78% of the $43.7B disclosed went to AI-related companies.
 Simon Hawtin
· 5 min readOriginal research
company funding rounds covered, 79 with a disclosed amount
TechCrunch coveragedisclosed in total. The median round was $100M
79 disclosed roundsof disclosed dollars went to AI-related companies. 66% without DeepSeek
DeepSeek $15B is reportedcame from just 11 rounds of $1B or more
$32.5B of $43.7B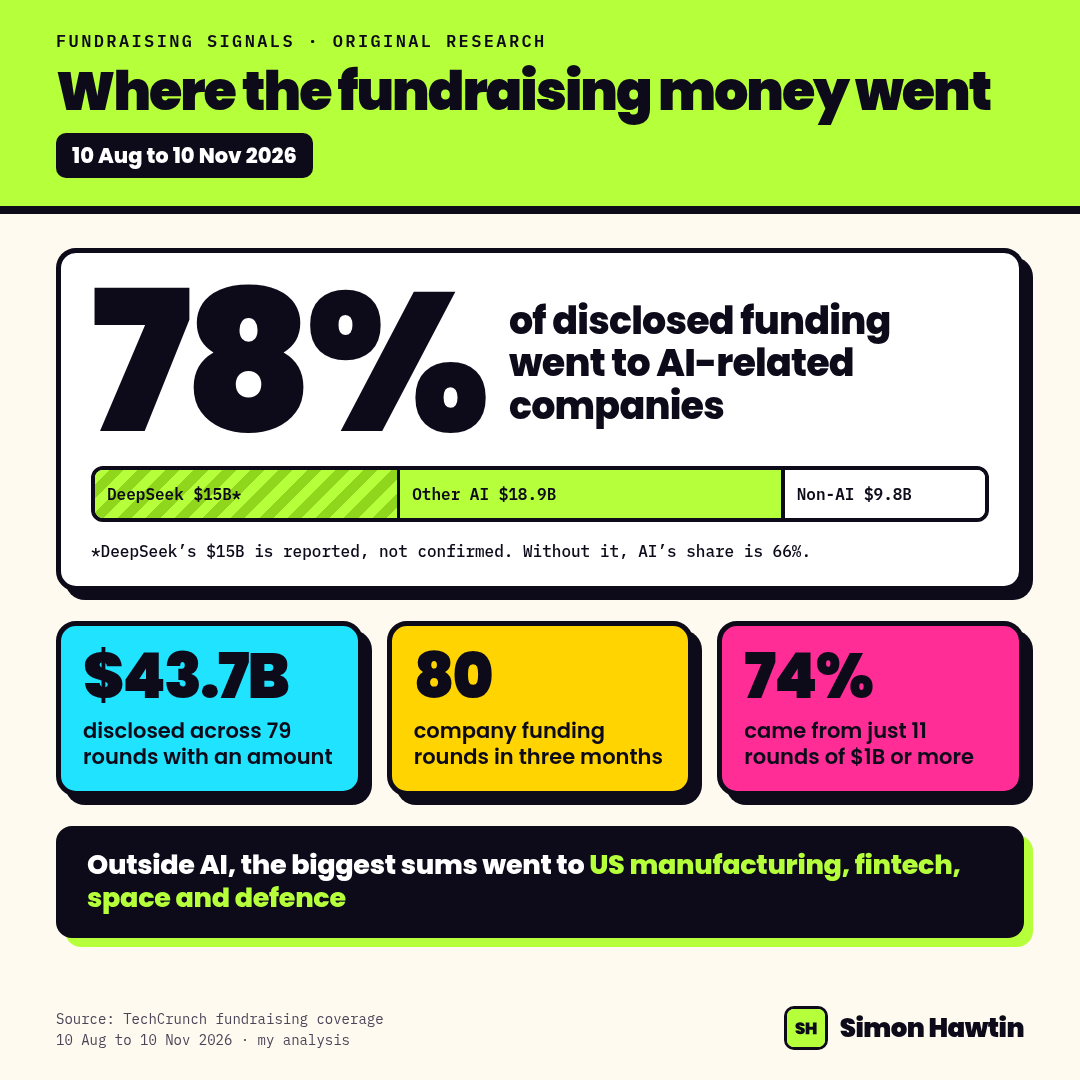
I went through every funding round TechCrunch covered in its fundraising category between 10 Aug and 10 Nov 2026. That came to 80 company funding rounds. 79 of them had a disclosed amount, and together they add up to $43.7B. The median round was $100M.
Most of the money went to AI
$33.9B of the $43.7B, or 78%, went to companies building or selling AI. By count it was 51 of the 80 rounds, so AI took a bigger share of the dollars than of the deals.
The biggest single sector was AI models and labs at $16.1B, but almost all of that is one company. Next were AI data and developer tools at $6.1B (mostly Databricks’s $5B), then applied AI and agents at $4.4B and AI compute and chips at $3.7B.
Disclosed funding by sector
79 rounds with a disclosed amount, $ millions/billions · TechCrunch fundraising coverage, 10 Aug to 10 Nov 2026
The DeepSeek caveat
The single biggest number here is DeepSeek’s $15B. That comes from a Bloomberg report and DeepSeek hasn’t confirmed it. I’ve counted it, but it moves the headline a lot. Take it out and the total is $28.7B, and AI’s share drops from 78% to 66%.
$33.9B of $43.7B went to AI-related companies.
$18.9B of $28.7B. Still two thirds.
A handful of very big rounds
11 rounds of $1B or more took $32.5B, which is 74% of everything disclosed. The top 10 alone hold 72%. At the other end, the 37 rounds under $100M add up to about $0.9B, roughly 2% of the total.
Share of disclosed dollars by round size
79 rounds with a disclosed amount
The 12 biggest rounds
- #Company · sectorAmountDate
- 1DeepSeekReportedAI models and labs · Chinese AI lab building open models$15B22 Oct
- 2DatabricksAI data and developer tools · Data and AI platform for enterprises$5B13 Aug
- 3Re:BuildIndustrial and manufacturing · Manufacturing accelerator building and launching hard-tech companies$2.1B27 Oct
- 4Thrive HoldingsApplied AI and agents · Buys traditional businesses such as accounting firms and adds AI$2B12 Aug
- 5RampFintech · Corporate cards, expense management, payments and AI finance tools$1.85B15 Oct
- 6TenstorrentAI compute and chips · AI inference chips and servers for open-weight models$1.5B19 Oct
- 7CastelionDefence · Lower-cost hypersonic missiles$1B20 Aug
- 8LambdaDebtAI compute and chips · AI cloud renting Nvidia GPUs$1B28 Aug
- 9Stoke SpaceInitial closeSpace and aviation · Fully reusable rockets$1B8 Sep
- 10InstinctConsumer apps and media · Consumer AI agent that completes tasks for users$1B28 Sep
- 11Flapping AirplanesAI models and labs · AI lab training large models with far less data$1B21 Oct
- 12Form EnergyClimate and energy · 100-hour iron-air grid batteries$750M12 Aug
Company names link to the TechCrunch article. “Reported” means the figure came from another outlet’s report, not the company.
October looks huge, mostly because of one round
October had the most rounds (29) and the most money ($24.2B). Take out DeepSeek and October drops to $9.2B, behind the last three weeks of August at $12.5B. 1 to 10 Nov had six rounds and just under $1B.
Disclosed funding by month
Striped part is DeepSeek’s reported $15B · October is $9.2B without it
What was busiest by number of rounds
Counting rounds rather than dollars gives a different picture. The busiest offerings were AI agents for business workflows, consumer AI assistants and AI training and evaluation data, with six rounds each, then inference chips and neoclouds and security for AI agents with five each.
The one that stood out to me is security for AI agents. Five companies raised for it in two months, from HiddenLayer on 2 Sep to Mintive on 29 Oct. If you’re rolling out agents in your own team, that tells you where the worry is.
Busiest offerings by number of rounds
My labels for what each company sells · all 80 rounds, including Factory with no amount
Outside AI
Outside AI, four areas each took around $2B: fintech ($2.15B, mostly Ramp’s $1.85B), US manufacturing ($2.1B, almost all Re:Build), space ($2.0B, led by Stoke Space’s $1B initial close) and defence ($1.8B, led by Castelion at $1B and Mach Industries at $600M).
Apart from Ramp, the money outside AI is going into physical things: rockets, missiles, factories and, a bit further down, grid batteries.
How I counted
I read pages 1 to 8 of TechCrunch’s fundraising RSS feed, 155 items in total. 144 fell between 10 Aug and 10 Nov 2026. I took out 50 TechCrunch event promos, read the other 94 articles and counted 80 company funding rounds.
The 14 I left out were rounds still in talks or not closed, VC fund closes, secondaries and stories that weren’t raises. Factory is counted with no amount because none was disclosed. Two figures are reported rather than confirmed, DeepSeek’s $15B (Bloomberg) and Polymarket’s $300M (WSJ), and I’ve counted both.
Sectors and offerings are my own labels. Only 33 of the 80 articles said where the company is based, so I haven’t broken this down by country. This is TechCrunch’s editorial coverage, not the whole private market.
Source: TechCrunch fundraising coverage, 10 Aug to 10 Nov 2026.
Simon Hawtin
Agentic GTM leader in London, using AI agents for signal-based outbound, ABM and AEO/GEO to acquire pipeline.